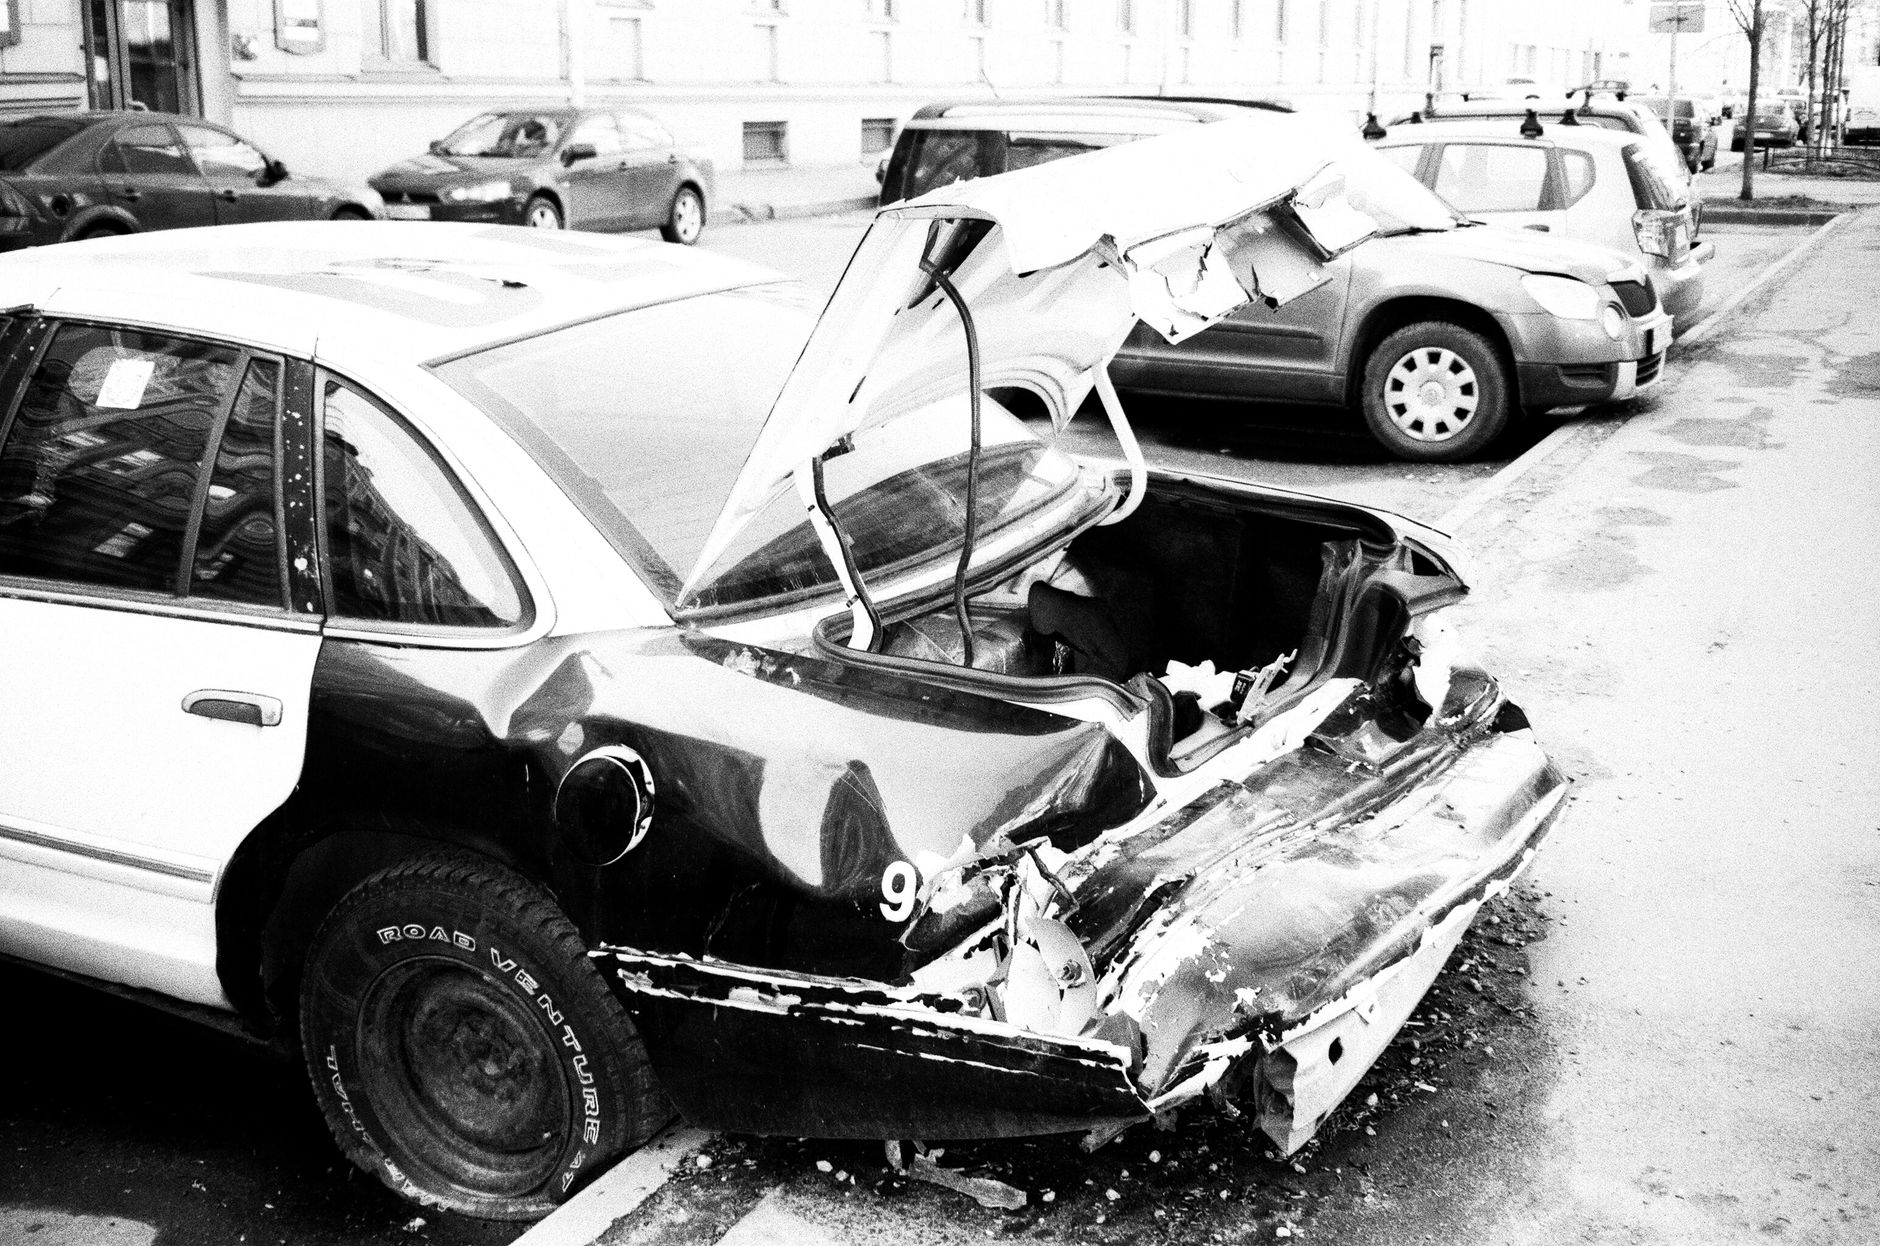
Many crash victims assume the at-fault driver’s insurance will pay for everything. Often it will not. When medical bills, lost income, and vehicle repairs climb past a policy’s maximum, you may be left covering the difference yourself.
You may still have ways to recover the full amount. Here is how these situations work and which steps are worth considering.
Why Insurance Limits Can Leave You Short
A policy limit is the most an insurer will pay on a claim. Once a claim reaches that number, the insurer owes nothing more, even if your losses are higher.
Most states require only minimum coverage, and those minimums are often far below the real cost of a serious crash. Limits are also divided between bodily injury and property damage, which can shrink the money available for your medical care.
When a claim exceeds insurance limits, the remaining losses have to be pursued through other channels.
Your Options When Damages Exceed Policy Limits
Several paths may be open to you. The right one depends on your coverage, your injuries, and the at-fault driver’s financial situation.
Use Your Own UM/UIM Coverage
If you carry uninsured or underinsured motorist (UM/UIM) coverage, you may be able to file a claim with your own insurer for the difference.
This protection exists for exactly this situation. It is not mandatory everywhere, though, so many drivers never buy it. Reviewing your own policy is a smart first step after any crash.
File a Personal Injury Lawsuit
You have the right to sue the at-fault driver directly for losses beyond their policy limits. A judge or jury can then decide the outcome.
Timing matters. Most states set a strict statute of limitations on injury claims, commonly about two years from the accident date. Miss that window, and you may lose the right to recover anything.
Look at Other Coverage Sources
Some additional sources can help close the gap:
- Medical Payments (MedPay) coverage pays immediate medical expenses regardless of who caused the crash.
- Umbrella policies extend liability protection beyond a standard auto policy, whether it belongs to the at-fault driver or to you.
A legal consultation can uncover options you might not know exist.
How Car Insurance Coverage Works
Knowing what your policy includes helps you plan before anything happens. Standard auto insurance usually has three main parts:
- Liability coverage pays for the other party’s injuries and property damage when you are at fault.
- Collision coverage pays for your vehicle repairs after a crash, regardless of fault.
- Comprehensive coverage pays for non-collision losses such as theft, vandalism, or weather damage.
Each part serves a different purpose. Understanding them shows you what protection you actually have.
What You Can Recover in a Lawsuit
When you take a case to court, you can seek two categories of damages.
Economic damages have a clear dollar value. They include medical bills, lost wages, and property damage.
Non-economic damages are harder to measure. They cover pain and suffering, emotional distress, and loss of enjoyment of life.
The amount you can recover depends on the facts of your case. The best personal injury law firm can compare your situation to similar cases and help set a realistic range for a settlement or verdict.
One caution applies. Winning a judgment does not guarantee payment. If the at-fault driver has few personal assets, collecting can be difficult. That is why it pays to look at every possible source of recovery early, including your own UM/UIM benefits.
How an Attorney Can Help
Handling a claim that exceeds policy limits is not something most people should try alone. Working with an experienced car accident lawyer or a firm in your own area, can give you guidance through each option and a stronger case for full compensation.
Here is what legal representation can add:
- Thorough case assessment. An attorney reviews every applicable policy, including liability, UM/UIM, and umbrella coverage, to find all possible sources of payment.
- Evidence gathering. From police reports to medical and economic experts, your legal team builds a case backed by solid proof of your losses.
- Strategic negotiation. Insurers often try to minimize payouts. An attorney can push back with demand letters, mediation, and direct negotiation.
- Trial representation. If a fair offer never comes, a lawsuit may be the only route to full recovery.
- Deadline compliance. Strict filing deadlines apply, and an attorney makes sure every document is filed on time so your rights stay protected.
Don’t Assume You’re Out of Options
If you were hurt in a crash and your losses are bigger than the at-fault driver’s coverage, you still have choices. A dedicated legal team can evaluate your case, identify every available source of compensation, and work to help you recover the full amount you deserve.